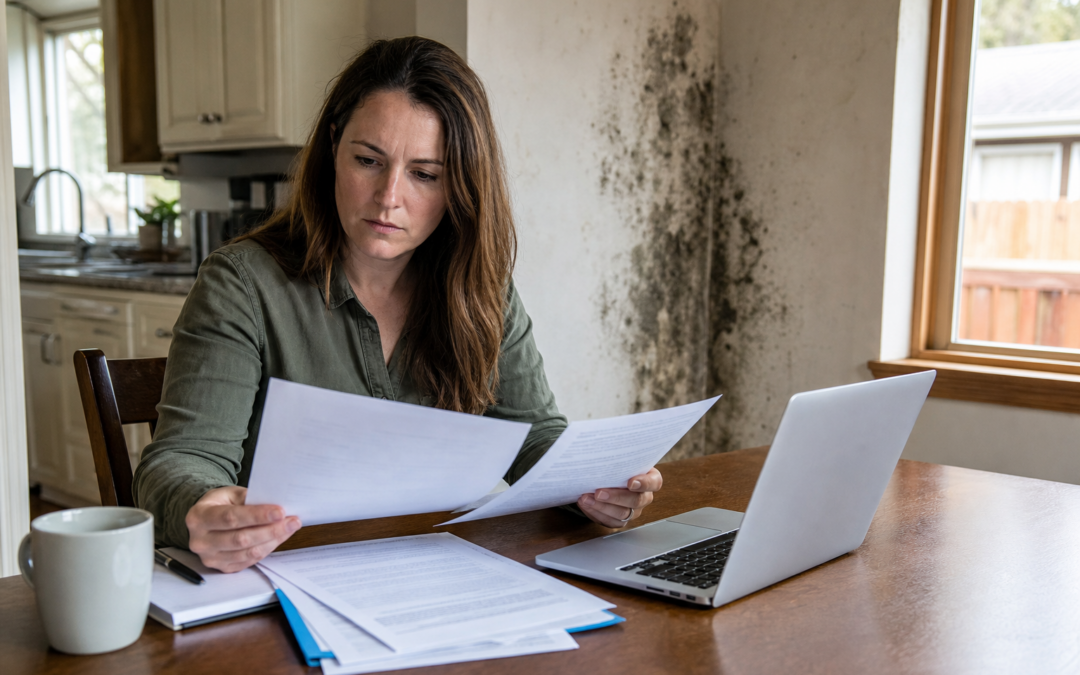
You found mold after a leak, you’ve gotten a quote for remediation, and now you’re staring at your policy trying to figure out whether any of this is covered. It’s a frustrating document to read, and the honest answer is the one nobody likes: sometimes.
But “sometimes” isn’t random. There’s a clear logic to which mold claims get paid and which get denied, and once you understand it, you can see where your situation falls — and what you can still do to protect your claim.
(A quick note: we’re a restoration company, not an insurance agency, and every policy is different. Read yours, and talk to your agent. What follows is what we see day to day working with carriers across Northern Colorado.)
The One Rule That Decides Almost Everything
Mold coverage almost always comes down to a single question: what caused the water, and was it sudden and accidental?
Standard homeowners policies cover damage from sudden, accidental events. They exclude damage from gradual deterioration and lack of maintenance. Mold isn’t usually treated as its own peril — it’s treated as a consequence. So the coverage follows the water.
Typically covered — mold resulting from a covered water loss:
- A burst or frozen pipe that split during a cold snap
- A water heater that failed suddenly
- A washing machine or dishwasher supply hose that let go
- A toilet supply line failure or sudden overflow
- Storm damage — a hail-damaged roof that let water in, or wind that tore off shingles
- Water damage from putting out a fire
Typically not covered:
- Long-term seepage. A drip under the sink that ran for months, a slow roof leak you knew about, a chronically damp basement wall.
- Deferred maintenance. Failed caulk around a tub, cracked grout in a shower, gutters that were never cleaned.
- Humidity and condensation. Poor ventilation in a bathroom or crawl space causing mold is considered a maintenance issue.
- Groundwater and flooding. Surface flooding is excluded from standard policies entirely — that requires separate flood insurance. This catches a lot of Colorado homeowners after heavy runoff.
- Sewer or drain backup — unless you carry the specific backup endorsement, which is inexpensive and worth having.
Why Mold Claims Get Denied More Often Than Water Claims
Even when the underlying water event is covered, mold gets scrutinized harder. Here’s why, and what actually trips homeowners up:
- Mold sublimits. Many policies cap mold remediation at a specific dollar figure — often a few thousand dollars — separate from and much lower than your dwelling coverage. Your water damage might be fully covered while the mold portion is capped. Check your declarations page for a mold or fungi limit.
- Delay. This is the big one. If you knew about the water and waited weeks to act, the carrier may argue the mold resulted from your delay rather than the covered event. Prompt action isn’t just good practice — your policy requires it.
- No proof of cause. If you can’t demonstrate the water came from a sudden failure, the default assumption is gradual damage. This is why keeping the burst pipe section or failed hose matters so much.
- Pre-existing conditions. If an adjuster sees old staining or prior growth, they may attribute the whole problem to a longstanding issue.
How to Protect Your Mold Claim
Whether or not you’ve had the leak yet, this is what makes the difference:
- Act immediately. Mold can begin growing in wet materials within 24 to 48 hours. Fast professional drying is the single best thing you can do for both your house and your claim.
- Document before you clean. Photos and video of the water, the source, and the affected areas — before anything is moved or torn out.
- Save the failed component. The cracked pipe, the split supply hose, the corroded fitting. It’s physical evidence of a sudden failure.
- Get professional moisture readings. Documented moisture-meter and thermal-imaging data showing how far water spread inside walls and floors is far more persuasive than photographs alone.
- Don’t scrub it yourself first. Beyond spreading spores through the house, altering the damage before it’s documented can weaken your claim.
- Keep a written log of every call, name, date, and decision.
- Ask your agent about a mold endorsement and a sewer backup endorsement before you need them. Both are usually cheap.
Call Us Before You Call Your Insurance Company
We say this a lot, and here’s the practical reason: when you call Revive first, we arrive with the equipment to establish and document the full scope of the loss — including moisture inside wall cavities and under flooring that no photo will ever show. That documentation goes into your claim file from day one, rather than being reconstructed later.
We also start drying right away, which limits how much mold has a chance to develop at all. Less mold means a smaller remediation scope, a smaller chance of running into your policy’s mold sublimit, and a much better outcome for you.
We work with all insurance carriers and we’re happy to talk directly with your adjuster.
Locally Owned, Available 24/7
Revive Restoration is family-operated and locally owned by Levi, born and raised in Northern Colorado. We respond around the clock with a 60-minute response time.
If you’ve found mold and you don’t know whether it’s covered, whether it’s serious, or where the water is even coming from — call us. We’ll come look, tell you honestly what we find, and the inspection is free.
Mold after a water leak? Call Revive Restoration at (720) 340-3499.
Serving All of Northern Colorado
We handle mold remediation and water damage across the Front Range, including Fort Collins, Loveland, Greeley, Windsor, Longmont, and Wellington. See every community we serve on our service areas page, or read more about our mold remediation services.