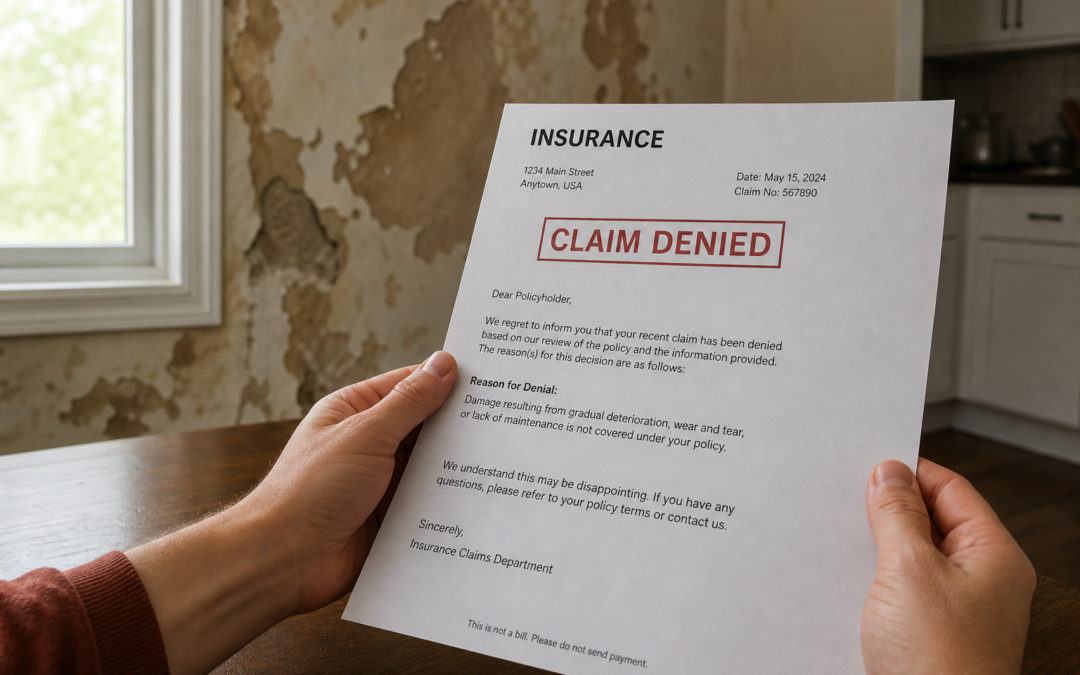
You did everything right. You had a covered loss, you filed the claim, you waited. And then the letter came: denied.
It’s a gut punch — especially when you’re staring at a soaked basement and a repair you can’t put off. But here’s what most Northern Colorado homeowners don’t know: a denial is not the end of the process. It’s the beginning of the appeal. Denials get overturned regularly, and usually for one reason — someone finally brought the right documentation.
Why water damage claims get denied
Understanding the reason on your letter tells you how to fight it.
- “Gradual damage” or “long-term seepage.” The most common denial by far. Most policies cover sudden and accidental water discharge, not slow leaks that happened over weeks or months. Carriers lean on this hard — sometimes correctly, often not. A pipe that burst last Tuesday can still get labeled gradual if the documentation is thin.
- “Lack of maintenance.” The carrier argues you should have caught it — an old water heater, a known drip, a roof past its service life.
- “Pre-existing damage.” They claim the damage predates the policy or the reported event, often based on old staining or a prior claim on the property.
- Flood exclusion. Standard homeowners policies do not cover surface flooding or groundwater. That requires separate flood insurance — a real distinction along the Front Range, where storm runoff and rising groundwater are common.
- Sewer or drain backup without an endorsement. Backup coverage is usually an add-on, not standard.
- Late reporting. Policies require prompt notice. Waiting weeks gives the carrier an easy out.
- Insufficient documentation. Sometimes the loss was covered and the file simply didn’t prove it. This is the most fixable denial of all.
- Mold limitations. Many policies cap mold remediation at a low dollar figure or exclude it unless it results from a covered water loss.
What to do first — the next 72 hours matter
- 1. Get the denial in writing, with the specific policy language. Don’t accept a phone explanation. Request the written denial letter citing the exact exclusion or provision they’re relying on. You can’t rebut an argument you haven’t read.
- 2. Request your complete claim file. The adjuster’s report, photos, moisture readings (if any were taken), engineer reports, and notes. Read what they actually documented. Very often the file is thinner than you’d expect.
- 3. Read your policy — the declarations page and the water sections. Look for what’s covered, what’s excluded, your deductible, and whether you have a sewer/drain backup endorsement or additional coverages you weren’t told about.
- 4. Get an independent professional inspection. This is the step that changes outcomes. A restoration company documents cause of loss, moisture mapping, affected materials, and scope of work with instruments and photos — evidence the carrier has to respond to.
- 5. Do not throw anything away yet. Removed drywall, carpet pad, the failed part itself — physical evidence supports your case. Photograph everything before disposal.
- 6. Write the appeal. A short, factual letter: the denial reason, the specific evidence that contradicts it, and the documentation attached. Ask for a re-inspection and reconsideration.
- 7. Escalate if needed. Request a different adjuster or a supervisor review. Colorado homeowners can also file a complaint with the Colorado Division of Insurance, which carriers take seriously. Public adjusters and policyholder attorneys are options for larger disputes.
Why documentation from a restoration company carries weight
An adjuster visits once, for maybe 30 minutes, and often isn’t a water damage specialist. A restoration contractor is on site over multiple days with moisture meters, thermal imaging, and hygrometers, generating daily readings.
That produces things an appeal actually needs:
- Objective moisture data that maps the true extent of water migration — including inside wall cavities the adjuster never opened.
- Cause and origin findings that can distinguish a sudden failure from long-term seepage. Water from a recent burst behaves differently than months-old chronic moisture, and a specialist can show it.
- Photo and thermal documentation timestamped from day one.
- An itemized, industry-standard scope and estimate in the same estimating software carriers use — so there’s an apples-to-apples comparison instead of a vague dispute.
- A written technical rebuttal to the specific exclusion cited.
“Gradual damage” denials in particular are frequently reversed when someone produces real moisture data showing a sudden event. Without that data, it’s your word against the adjuster’s — and that isn’t a fight you win.
The best way to avoid a denial: call us first
Here’s the pattern we see over and over. A homeowner finds water, calls the insurance company immediately, and describes damage they haven’t fully assessed yet — “some water in the basement.” The claim gets opened on that description, the adjuster inspects what’s visible, and the scope is set too small. Everything after that is an uphill argument.
Call Revive Restoration before you call your insurance company. We’ll inspect for free, document the full scope with meter readings and photographs, identify the cause of loss, and give you a straight answer about what you’re dealing with — all before anything is reported. Then the claim gets filed accurately the first time.
And if you’ve already been denied? Bring us the letter. We do these inspections every month, we know what adjusters look for, and we work with all major carriers. Sometimes the denial is correct and we’ll tell you so honestly — along with your options. Often it isn’t.
Don’t accept a denial without a second opinion
A denial letter is one company’s opinion, formed from limited information. You are allowed to challenge it, and homeowners who challenge it with real evidence win more often than you’d think.
Free inspection, 24/7, across Northern Colorado. Call Revive Restoration at (720) 340-3499 before you accept a denial.